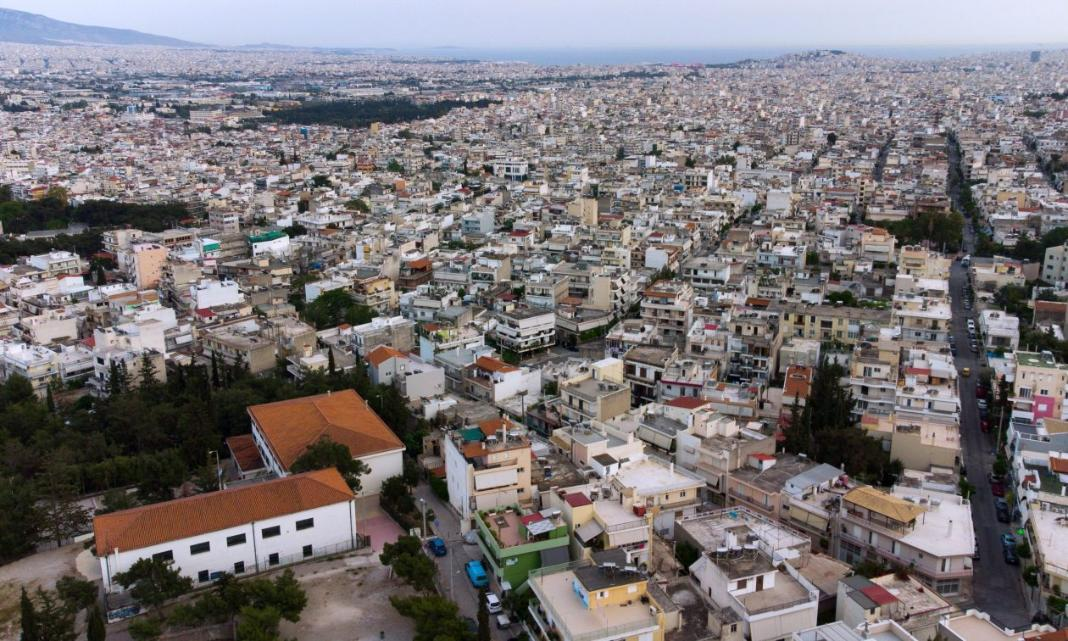
The Eurogroup’s decision to place the Mediterranean housing crisis at the top of its economic agenda is an acknowledgment of an unsustainable reality. According to recent Eurostat data, Greece leads the European Union in housing cost overburden, with over 40% of the population spending more than 40% of their disposable income on housing costs.
However, the most critical figure tying the hands of policymakers is the structural deficit of the market itself: Greece is currently facing a shortage of approximately 794,000 homes. When a housing market is short nearly 800,000 physical units, any financial model proposed by Brussels risks becoming a placeholder rather than a solution.
The Concession Delusion: The Scaling Problem of Public Plots
The Eurogroup’s first model focuses on supply-side intervention through Public-Private Partnerships (PPPs). The framework suggests leveraging state-owned land assets to attract private construction firms. In exchange for tax exemptions, developers build modern blocks, locking a fixed percentage—typically 30% to 40% of the units—into social housing programs with capped rents for 30 years, while selling the remaining stock at market rates.
In Athens, this model immediately hits a geographical and physical wall. The city center has an urban density exceeding 19,000 people per square kilometer in areas like Kypseli, leaving almost zero unutilized municipal plots large enough to justify industrial-scale residential construction. Against a nationwide deficit of 794,000 units, localized PPP projects in outer peripheral zones or the western suburbs are a drop in the bucket. They add minor physical stock to the overall macro supply but do nothing to ease the intense, immediate demand for central residential units near Metro Line 2 and 3 stations.
The Tax Holiday Trap: Capped Leases vs. €1,200 Summer Yields
The second model attempts to rebalance the existing housing stock by offering income tax breaks to individual property owners who pull their listings off short-term tourist platforms. The Eurogroup is discussing a framework that would exempt landlords from a portion of the standard rental income tax—which in Greece scales sharply from 15% up to 45% for revenues over €35,000.
For a landlord in central districts like Koukaki or Neos Kosmos, the math of this incentive rarely adds up. A renovated 50-square-meter apartment on a long-term civil lease in these areas caps out at around €600 to €800 a month. The same property operating on short-term platforms during the peak May-to-September tourist season regularly generates €1,200 to €1,800 a month. A tax credit of a few percentage points cannot bridge this revenue gap. With a macro deficit of 794,000 homes, the state needs to claw back hundreds of thousands of apartments to make a dent, but individual owners have little financial incentive to trade high-liquidity tourist cash for a capped, multi-year civil contract.
Subsidizing Credit in a Zero-Stock Market
The final pillar of the Eurogroup framework focuses on demand-side support, expanding subsidized, low-interest mortgage funds for buyers under the age of 40. This is an expansion of cross-border funding mechanisms modeled after Greece’s initial €1 billion “Spiti Mou” program, which quickly exhausted its budget due to overwhelming demand.
The economic risk here is quantifiable. Injecting cheap, state-backed credit into a real estate market with a 794,000-unit supply shortage simply drives price inflation. During the first phase of local housing credit expansions, asking prices for post-2000 unrenovated units in middle-tier Athenian suburbs spiked by 10% to 15% within a six-month window. Because the supply of available two-bedroom apartments remains fixed, the state subsidy is instantly absorbed by property inflation. The young buyer ends up carrying the same high debt load, while the state funding effectively serves as a direct liquidity injection for the existing property sellers.
Practical Reality
The Eurogroup’s focus proves that housing costs in Southern Europe have reached a threshold that threatens broader economic stability. However, European structural funds require months of legislative alignment before any local capital is cleared for disbursement.
For the modern resident navigating Athens today, these macro models offer zero immediate relief. Bridging a gap of 794,000 homes through physical infrastructure or tax shifts takes years to materialize on the street. Success in the current Athenian market continues to depend entirely on immediate decision-making, clear liquidity for deposits, and looking beyond the oversaturated central core, rather than waiting for a Brussels funding mechanism to fix a broken domestic supply chain.