The Eurogroup’s theoretical models for resolving the Mediterranean housing crisis have been met with a cold mathematical reality check. Recent domestic market data highlights a stark benchmark for the local workforce: it now takes an average Greek citizen 19 years of dedicated saving just to accumulate the standard 20% down payment required for a basic apartment footprint.
When the financial barrier to entry requires nearly two decades of capital accumulation before a mortgage can even be initiated, the housing crisis in Greece ceases to be a cyclical issue. It has evolved into a structural exclusion of an entire generation from the property market.
The Cold Math Behind the 19-Year Benchmark
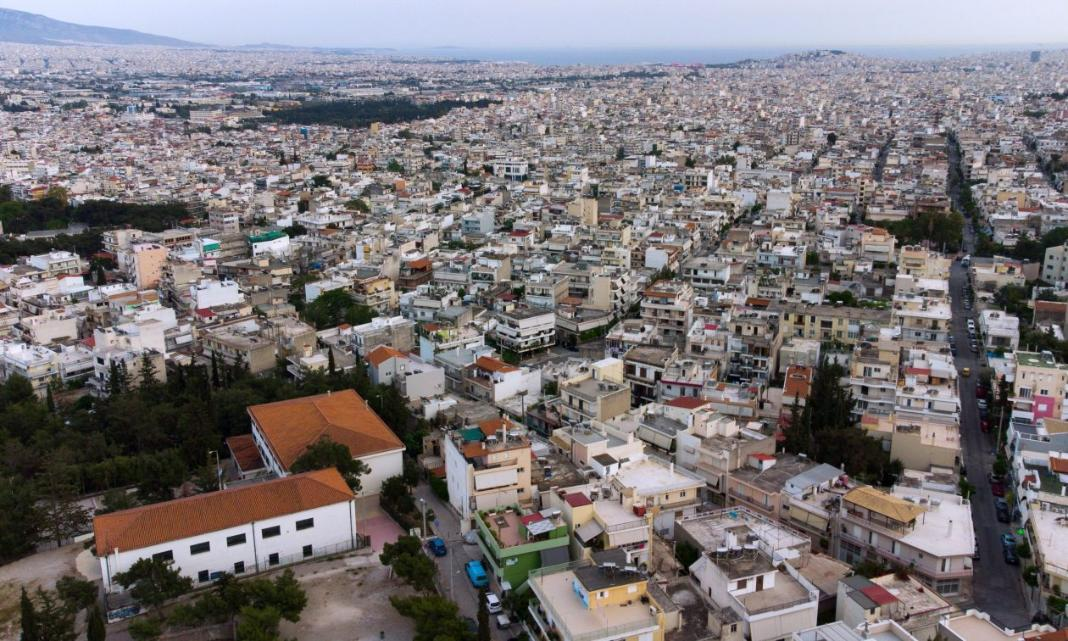
To understand how the market reached this 19-year calculation, you have to look at the divergence between wage stagnation and property inflation across Attica.
The Real Value Gap * Average Net Monthly Salary: Approximately €900 to €1,100 for young to mid-career professionals.
- Average Cost of a 1-Bedroom Apartment (Post-2000/Renovated): €150,000 to €180,000 in non-luxury residential districts like Ambelokipi or Marousi.
- The Required 20% Down Payment: €30,000 to €36,000 in cold cash, excluding bank setup fees, notary costs, and the 3% property transfer tax.
In practice, with the rising cost of living in Athens—where basic groceries, volatile utility bills, and unrenovated rental costs eat up over 60% of a single income—the realistic monthly savings capacity of a local worker caps out at €150 to €200. Mathematically, saving €36,000 at a rate of €150 a month takes exactly 20 years. The 19-year benchmark isn’t an exaggeration; it is a literal description of local bank balance sheets.
Why Subsidized Loans Fail the 19-Year Test
This 19-year deposit barrier explains why demand-side interventions, such as the state-backed low-interest loan programs for buyers under 40, are failing to solve the broader crisis.
While these state initiatives offer cheap credit for the remaining 80% of the property value, they do not eliminate the need for the initial upfront liquidity. Young professionals without substantial family wealth (the traditional Greek antiparochi or inherited property safety net) simply cannot cross the threshold of the initial deposit.
Furthermore, because Greece is facing an absolute inventory deficit of 794,000 physical homes, injecting state-backed buyers into the market has had a predictable counter-effect. Sellers aware of these loan programs instantly inflate their asking prices, meaning a €30,000 deposit requirement quickly jumps to €40,000, resetting the savings clock for the buyer.
The Shift to a Permanent Rental Class
The immediate structural consequence of this 19-year savings trap is the forced professionalization of the rental market. Because buying has become mathematically locked away, professional inventory is being consolidated by international funds and high-liquidity cash buyers who face no such savings timelines.
Local families and young professional couples who historically would have transitioned into property ownership by their early 30s are remaining in the rental pool indefinitely. This permanent retention of high-earning tenants in the rental sector is keeping the floor price for affordable rent Athens handles incredibly high, preventing rental rates from dropping even during the winter off-season.
The market has entered a closed loop: high rents prevent tenants from saving for a deposit, and the inability to pay a deposit forces them to keep renting.
The Understated Outlook
The 19-year deposit benchmark exposes the gap between macroeconomic recovery headlines and the street-level reality of living in Athens today. Property values are no longer scaling with the domestic economy; they are scaling with global investment flows and corporate developments.
For the resident trying to navigate the city, waiting for a market correction or a policy fix is an inefficient strategy. The numbers show that the barrier to entry is fixed and unforgiving. Securing housing stability in Athens now requires a complete departure from traditional purchase expectations, forcing a reliance on alternative models like managed shared living or pivoting entirely to the unrenovated periphery where the entry floor has not yet completely locked out local wages.